Electronic Contract Manufacturing Service Provider in California

China Top 10 Monolithic Integrated Circuit Manufacturers

China’s Monolithic Integrated circuit industry now spans advanced logic, memory, power management, sensors, and automotive electronics. Its factories support products found in smartphones, electric vehicles, industrial controls, and household appliances. This article introduces ten influential Chinese manufacturers and explains their different strengths.

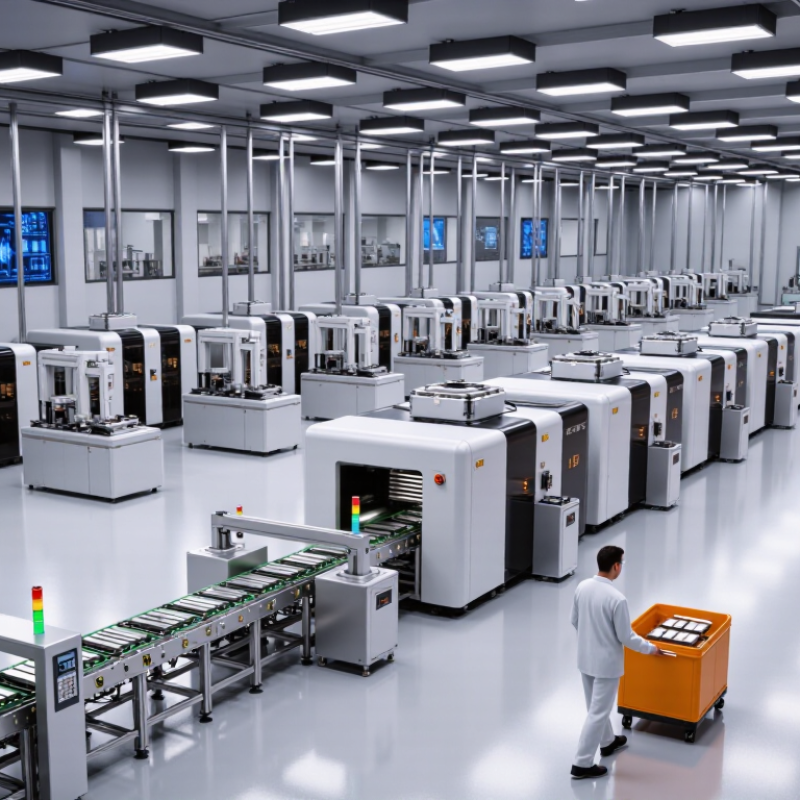
The list considers wafer capacity, process capability, product focus, customer reach, and manufacturing reliability. Major names may include SMIC, Hua Hong Semiconductor, Nexchip, Silan Microelectronics, and other specialized producers. Some companies operate large wafer fabs, while others focus on analog chips, power devices, or integrated design and manufacturing. A cleanroom may look quiet, yet each wafer passes through hundreds of tightly controlled steps.

Small errors matter.

As Nobel Prize-winning engineer Jack Kilby said, “The integrated circuit was born out of a need to solve a problem.” His observation still reflects the industry’s practical purpose. Monolithic Integrated technology combines multiple functions on one semiconductor substrate, reducing size, wiring complexity, and energy loss. China’s manufacturers are improving equipment access, process consistency, packaging, and domestic supply chains. Their progress is significant, but it is not uniform. Some companies lead in mature-node production, while others continue narrowing gaps in advanced processes. Ranking these manufacturers is therefore difficult. Public data can be incomplete, and “top” may mean capacity, revenue, technology, or market influence. Readers should treat this overview as a structured industry guide, not an absolute verdict. The most useful comparison examines real products, verified production capability, and long-term customer performance.
China Top 10 Monolithic Integrated Circuit Manufacturers

Monolithic Integrated Circuits: Definition and Core Characteristics

Monolithic Integrated Circuits place transistors, resistors, capacitors, and interconnections on one semiconductor die. This structure differs from hybrid circuits, which combine separately manufactured components. For engineers comparing China’s leading ten manufacturers, this definition provides a practical starting point.

Their core strength is compact integration. Short internal connections can reduce parasitic capacitance, improve signal speed, and lower power consumption. A single die also supports consistent electrical behavior during mass production. However, heat remains a serious concern. Dense layouts may create hot spots, especially in power-management or high-frequency applications. Fabrication accuracy, wafer cleanliness, packaging, and final testing all affect reliability. The term “monolithic” sounds simple, but real performance depends on many production details.

Tips: Check the process node, operating temperature, tolerance data, and qualification reports before choosing a device. Compare measured results with datasheet values, not attractive marketing claims. Engineers should also inspect thermal resistance and long-term drift. A common mistake is focusing only on integration density. That approach can miss noise, heat, or repair limitations. Some comparisons remain imperfect because public manufacturing data is incomplete. Careful testing is still necessary.
China Top 10 Monolithic Integrated Circuit Manufacturers

Monolithic Integrated Circuits: Definition and Core Characteristics

This chart presents representative industry-wide integration milestones rather than company or brand data. It shows how monolithic ICs evolved from thousands to billions of transistors as manufacturing feature sizes became smaller. A monolithic integrated circuit places active devices and interconnections on a single semiconductor die, enabling compact size, high reliability, and large-scale functional integration.

China’s Monolithic IC Industry: Development and Market Scope

China’s monolithic integrated circuit industry has moved from basic assembly toward deeper wafer fabrication and design capabilities. These circuits place multiple functions on one silicon die, improving size, speed, and production efficiency.

The market now serves automotive electronics, industrial controls, smart appliances, communications equipment, and energy systems. Automotive applications demand stable performance across heat, vibration, and long operating cycles. Industrial customers often value long-term supply more than rapid product updates. Consumer devices create higher volume, but pricing pressure remains intense. The picture is uneven. Some production lines use advanced process control, while others still face limits in yield, materials, or testing capacity.

A reliable review of China’s top ten monolithic IC manufacturers should examine more than revenue or factory size. Useful indicators include wafer capacity, process maturity, quality certifications, defect rates, and customer qualification records. Engineering support also matters when a device must operate inside a crowded control cabinet or a vehicle battery system. Public disclosures can be incomplete. That limitation matters. Market rankings may change when private capacity, regional investment, or contract production is counted differently. The industry still faces pressure from equipment access, specialized talent shortages, and complex supply-chain coordination. Manufacturers with strong domestic testing networks may gain practical advantages, even without the most advanced process nodes. A careful assessment should verify production consistency, delivery records, and application-specific reliability data.

China Top 10 Monolithic Integrated Circuit Manufacturers - China’s Monolithic IC Industry: Development and Market Scope

Rank Anonymous Manufacturer Profile Primary IC Categories Typical Application Markets Main Process Range Common Wafer Size Typical Packaging Development Strength Market Scope in China
1 Profile A Microcontrollers, embedded control ICs, mixed-signal devices Industrial automation, home appliances, automotive electronics 180–40 nm 8-inch / 12-inch QFN, QFP, BGA, wafer-level packages High-volume mature-node production and local design support Strong demand from consumer, industrial, and automotive supply chains
2 Profile B Power management ICs, battery-management ICs, charging ICs Mobile devices, energy storage, electric vehicles, power supplies 350–55 nm 8-inch / 12-inch QFN, DFN, TSSOP, wafer-level packages Broad analog portfolio and high-efficiency power architectures Rapid expansion supported by electrification and renewable-energy demand
3 Profile C Display driver ICs, touch controllers, interface ICs Smartphones, tablets, monitors, televisions, automotive displays 180–65 nm 8-inch / 12-inch COF, COG, QFN, wafer-level packages High-volume integration of display, touch, and connectivity functions Large domestic electronics ecosystem with significant export exposure
4 Profile D Analog signal-chain ICs, amplifiers, data converters Test equipment, communications, medical electronics, industrial control 180–40 nm 8-inch / 12-inch SOIC, TSSOP, QFN, BGA Precision, low-noise, and high-reliability analog design Supported by industrial upgrading and demand for domestic components
5 Profile E Discrete power devices, gate drivers, automotive power ICs Electric vehicles, chargers, photovoltaic systems, industrial drives 0.35 μm–90 nm 6-inch / 8-inch TO, DPAK, DFN, QFN, power modules High-voltage operation, thermal management, and automotive qualification One of the fastest-growing application areas due to energy transition
6 Profile F Connectivity ICs, radio-frequency front-end ICs, sensor interfaces Wireless equipment, smart devices, Internet of Things, industrial sensing 180–55 nm 8-inch / 12-inch QFN, WLCSP, BGA, flip-chip packages Integration of analog, digital, and radio-frequency functions Expanding with smart manufacturing, connected vehicles, and IoT deployment
7 Profile G Security ICs, secure elements, identification and authentication ICs Financial services, identity systems, transportation, connected devices 180–40 nm 6-inch / 8-inch Contact, contactless, QFN, embedded packages Hardware security, encryption, tamper resistance, and secure provisioning Stable domestic demand driven by digital payments and trusted computing
8 Profile H Memory control ICs, EEPROM, NOR and specialty memory devices Consumer electronics, automotive systems, industrial equipment 180–40 nm 8-inch / 12-inch TSOP, BGA, WSON, wafer-level packages Non-volatile memory reliability and long-life-cycle products Strategic market with opportunities in automotive and industrial substitution
9 Profile I Automotive sensing ICs, motor-control ICs, interface controllers Electric vehicles, intelligent transportation, battery systems, chassis electronics 350–55 nm 8-inch / 12-inch QFN, SOIC, automotive-grade QFP, power packages Automotive-grade reliability, temperature tolerance, and functional safety High-growth segment supported by vehicle electrification and intelligence
10 Profile J Optical sensing ICs, image-signal interfaces, environmental sensors Wearables, smart appliances, medical devices, industrial monitoring 180–65 nm 6-inch / 8-inch QFN, LGA, BGA, chip-scale packages Low-power sensing, compact integration, and application-specific design Emerging scope across healthcare, smart homes, and industrial IoT
Scope note: Manufacturer identities and brand-specific information are intentionally omitted. Process nodes, wafer sizes, package types, and application categories are presented as representative industry ranges for China’s monolithic IC sector.

Criteria for Ranking China’s Top 10 Monolithic IC Manufacturers

China Top 10 Monolithic Integrated Circuit Manufacturers

Ranking China’s top monolithic IC manufacturers requires more than comparing annual revenue. The scope should include companies designing and producing integrated circuits on a single semiconductor substrate. Module assemblers and pure distributors should be excluded. China Semiconductor Industry Association data reported that China’s integrated circuit industry reached approximately RMB 1.42 trillion in sales in 2023. This figure shows market scale, but it cannot identify manufacturing strength by itself.

A practical ranking should assign measurable weights. Revenue and shipment value may represent 25 percent. Wafer capacity, process capability, and verified yield should represent another 25 percent. R&D investment, patent quality, and engineering talent deserve 20 percent. Product reliability, customer diversity, certification records, and delivery stability should complete the framework. WSTS estimated global semiconductor sales at about 626.9 billion US dollars in 2024, highlighting the importance of comparing domestic performance with global demand. Data should come from audited filings, industry surveys, and factory records whenever possible.

No ranking is perfect. Public disclosures remain uneven, especially for privately held manufacturers. A company with lower revenue may possess stronger technology or better yield. That difference matters. Quarterly volatility can also distort annual results. The final list should therefore combine three-year averages, independent verification, and expert interviews. This approach is slower, but more credible. Even then, judgment remains necessary.

Profiles of China’s Top 10 Monolithic IC Manufacturers

China’s top ten monolithic IC manufacturers should be assessed by capability, not publicity. Industry rankings often combine foundry revenue, product sales, and manufacturing capacity. China Semiconductor Industry Association data placed the domestic integrated circuit industry at about RMB 1.05 trillion in sales in 2023, an 18% annual increase. Ranking remains debatable.

The ten profiles represent different strengths. One focuses on mature-node wafer production for industrial controls. Another develops advanced logic processes, where yield remains the hardest test. A third specializes in power devices for vehicles and energy systems. Two companies concentrate on analog and mixed-signal circuits, requiring stable parameters and long qualification cycles. The remaining profiles cover memory, microcontrollers, display drivers, image sensors, and radio-frequency devices. Each serves a distinct supply-chain need.

Manufacturing evidence matters. Buyers should examine wafer starts, defect density, process qualification, packaging control, and delivery consistency. Automotive projects may require years of testing before volume orders begin. The World Semiconductor Trade Statistics organization reported global semiconductor sales of approximately 526.9 billion dollars in 2023, showing the market’s scale and volatility. China’s growth is substantial, but imported equipment, design software, and advanced materials still create pressure points. Some profiles also disclose limited information, making comparisons imperfect. That weakness deserves attention, not concealment.

Key Applications, Technologies, and Industry Trends

China’s top monolithic integrated circuit manufacturers serve automotive, industrial, communication, and consumer electronics markets. Their products combine amplifiers, regulators, converters, sensors, and control functions on one silicon die. These devices reduce board space and improve signal consistency. In factory equipment, they monitor motor current and temperature. In vehicles, they support battery management, lighting control, and safety monitoring.

Current development focuses on lower power consumption, mixed-signal integration, and stronger resistance to heat and vibration. Advanced packaging also improves thermal performance when chips operate inside compact devices. Domestic manufacturers increasingly invest in mature process nodes, specialty materials, and reliable testing systems. These technologies may not always lead in tiny geometries, but they often fit practical industrial needs. No ranking stays permanent. Production stability, qualification records, and technical support can matter more than headline performance.

Tips: Check operating temperature, voltage tolerance, lifecycle data, and certification records before choosing a device. Test samples under real load conditions, not only in laboratory settings. Engineers should also review supply continuity and replacement options.

Industry trends show growing demand for power management, edge sensing, and intelligent control. Renewable energy equipment needs efficient conversion and monitoring circuits. Smart factories require chips that communicate with sensors in noisy environments. However, some market forecasts remain optimistic, and actual adoption can be slower than expected. This gap deserves careful review. Reliable manufacturers usually provide traceable testing data, application guidance, and clear failure analysis.